AlixPartners study reveals impact of GLP-1 medications on apparel brands

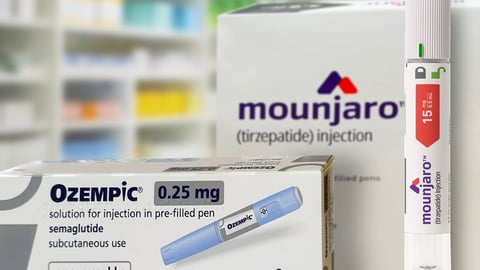
GLP-1 medications are reshaping apparel sizing and inventory — including cooling demand for inclusive, or plus, sizes.
That’s one of the findings of AlixPartners’ Consumer Sentiment Index, which found that the widespread adoption of the weight-loss medications is creating a moving target for apparel companies, many who are already contending with “bracketing” behaviors, in which consumers order multiple sizes and return the ill-fits. (According to Gallup, 11% of U.S. adults currently use GLP-1 medications for weight loss.)
Among activewear shoppers, the importance of inclusive product options declined from 55% in 2024 to 37% in 2026. At the same time, the importance of consistent fit and sizing rose from 29% in 2025 to 54%.
In related findings, 90% of boomers and Gen X women call consistent fit and sizing an important purchase driver. That compares to 78% of Gen Z and millennial women, with the 12% gap reflecting with where GLP-1 adoption is concentrated, noted AlixPartners.
Interest in services such as alterations also increased 29% versus last year. The increase rose fastest in the two categories most exposed to GLP-1 side effects: Outdoor & active and specialty.
AlixPartners' analysis of retail assortments found declines in plus-size offerings at H&M (-5% on two years prior), ASOS (-32%) and Reformation (-60%). .
[READ MORE: GLP-1 users are switching to these apparel retailers]
“One potential result of this trend may be that plus-size consumers find themselves excluded from up-market brands, while brands with a size-inclusive mission stand to lose customers as they shrink,” the firm said.
While bodies are in flux, consumers are more interested in two categories unaffected by weight loss: accessories and jewelry. Consumers say they expect to spend more in both categories, 50% and 54% respectively.
Research Methodology
Between July 14-24, AlixPartners surveyed more than 9,000 consumers on their preferences and priorities across 140 retailers and nine retail sectors: accessories, jewelry, luxury, footwear, outdoor and active, specialty, department store, mass and club, and off-price.
The research examined how consumers rank and prioritize five key pillars of retail performance — access, experience, service, product, and price — to identify shifts in sentiment and purchase drivers across categories.