Finance & Capital Management

  • Office Depot on the hunt for a CEO

    Office Depot has joined Staples in the search for a new chief executive.   Office Depot announced Monday that Roland Smith plans to retire as CEO of the company.  In June, Staples CEO Ron Sargent stepped down and the chain is still looking for a successor. The resignations come several months after the merger between the two retailers was dropped over antitrust concerns.  
  • Big merger announced in convenience store industry

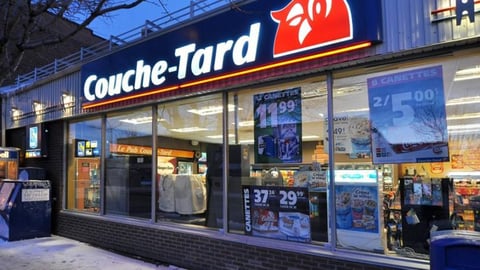
    Alimentation Couche-Tard Inc. is expanding its U.S. portfolio yet again.   In its biggest acquisition to date, the Canadian convenience store retailer has agreed to buy CST Brands Inc. for $48.53 per share in cash, with the total deal valued at $4.4 billion, including debt.   Couche-Tard operates more than 12,000 locations globally under several brands, including Circle K. Last year, Couche-Tard acquired The Pantry for about $1.7 billion, including debt, adding more than 1,500 stores to its U.S. footprint.
  • Dollar General expands into North Dakota

    Dollar General is moving into North Dakota, announcing that it has begun construction on five new stores in the state. This gives the discount retailer a footprint in 44 states after having established operations in Maine, Oregon, and Rhode Island in 2015.   The initial North Dakota locations will be in Ellendale, Gwinner, Hankinson, Hillsboro, and Oakes. They’re being built in the chain’s standard 9,100-sq.-ft. format.  
  • Macy’s nabs Toys ‘R’ Us exec as new CMO

    Marketing in the department store arena may be new for Rich Lennox, but he’s got plenty of retail marketing experience under his belt. The CMO for Toys “R” Us, who also served in the same capacity for Zales Corp., will take the marketing reins of Macy’s Inc., effective Sept. 15.   Lennox, 51, succeeds Martine Reardon, who left Macy’s in May. He will lead a branding and marketing strategy charge across all channels, reporting to president Jeff Gennette.  
  • Tuesday Morning sees Q4 top-line advances

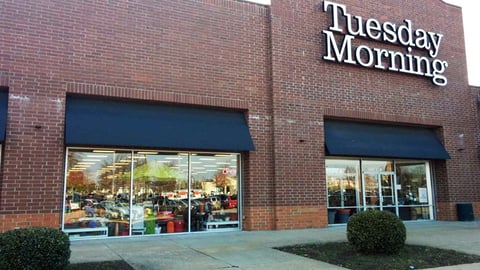
    Citing costs due to strategic rebuilding initiatives, Tuesday Morning Corp. reported a loss of $3.9 million in the fourth quarter ended June 30; however, revenue edged up to $222.8 million and same-store sales increased 6%.   According to CEO Steve Becker, pre-announced priorities – including real estate, merchandising, marketing, infrastructure and talent – continue to stay at the forefront of the chain’s activities and have positively impacted top-line performance.    
  • Hibbett Sports tops Q2 profit forecasts

    Hibbett Sports reported fiscal second-quarter net income of $6.5 million, beating Wall Street expectations.   The sporting goods retailer posted revenue of $206.9 million in the period, a 3.9% increase but falling short of Street forecasts. Analysts expected $210.1 million.   Same-store sales inched up 0.8%.  
  • At Home Depot, a big-ticket surge

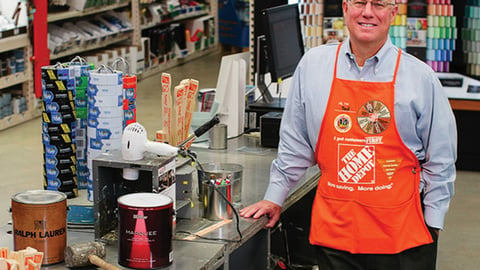
    Home Depot's chief merchant Ted Decker pointed to solid performance of core maintenance and repair categories, as well as many pro-focused categories during the second quarter.   So it's no wonder he said the company was "pleased" with its Q2 results.  
  • CVS Pharmacy commits $100,000 to Baton Rouge relief efforts

    CVS Health and the CVS Health Foundation on Thursday announced a $100,000 donation in cash and in-kind support to organizations providing relief efforts to flood victims in central Louisiana, including the Salvation Army USA Southern Territory and the American Red Cross.

  • Post-online jobs report: 1.2 million fewer retail workers

    If online retail didn’t exist, 1.2 million more people would be working in the retail industry.   Online productivity is that much higher, according to J.P. Morgan Chief U.S. Economist Michael Feroli. He told MarketWatch that revenue per online employee is four times greater than the brick-and-mortar variety: $1,267,000 to $279,000.
  • Report: Macy’s upcoming store closures turns up heat on debt

    Macy’s recently announced plans to close some 100 stores could do more than leave developers looking for a new anchor.   Nearly $30 billion of bonds backed by commercial mortgages are exposed to the retailer, reported Bloomberg, citing a note by Morningstar Credit Ratings. And more than $3.6 billion in loans would be affected by the closing of 28 stores that Morningstar identified as being most at risk, the report said. 
X
This ad will auto-close in 10 seconds